
Key Points
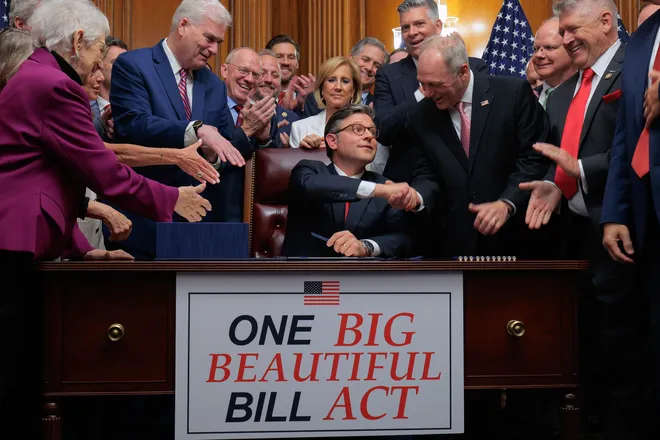
– The One Big Beautiful Bill Act of 2025 (OBBBA) introduces new rules for charitable donation tax deductions.
– Individuals 70½ or older can still make tax-free Qualified Charitable Distributions (QCDs) from their IRAs, which can count toward their RMD.
– Starting in 2026, non-itemizers can deduct up to $1,000 per person for cash donations in addition to the standard deduction.
– For itemizers, new limitations beginning in 2026 may reduce the tax benefit of charitable donations based on income.
Q. I understand there were changes made to deductions for charitable gifts in the new tax law. I usually give to my church out of my IRA in December, but my neighbor said I should wait until next year to donate because there is a new deduction. Is that true? — Mandy in Viera
A. That is only partially correct, Mandy.
It is true that in addition to several other changes to tax law, the One Big Beautiful Bill Act of 2025 (OBBBA) creates new ways to handle charitable donations. However, since you have been making Qualified Charitable Distributions (QCD) from your IRA, delaying a gift until next year may not be wise.
Making QCD is a tax-smart way for anyone 70½ or older to fund organizations they want to support. Usually, distributions from your IRA are taxable. However, donations made as a QCD are not taxable. Each eligible individual IRA owner can make an unlimited number of distributions from their IRAs to an unlimited number of qualified charities, up to a cumulative total per IRA owner of $108,000 in 2025.
For those subject to Required Minimum Distributions (RMD), the donation counts toward the RMD despite not being taxable. Moreover, QCD are particularly powerful because the donated amounts are completely ignored in the calculation of gross income on the tax forms.
See, as your Adjusted Gross Income (AGI) increases, a number of items are affected. For instance, you may lose deductions, increase taxes on capital gains, incur additional taxes on investment income, or trigger an IRMAA surcharge (higher Medicare premiums). The OBBBA has several new provisions that are affected by AGI including the new “enhanced senior deduction of $6,000 per person for taxpayers over 65 ($12,000 per couple if both are 65+) which can phase out as AGI rises.
So, if you were planning on making donations from your IRA again this year and those donations will cover some of your RMD, you should proceed as planned. That will be better than waiting to use the new deduction for non-itemizers that starts in 2026 because QCD uses pre-tax funds while the new deduction is paid from after-tax funds.
For non-itemizers, beginning in 2026, the OBBBA provides a deduction for charitable donations of cash (checks and credit card donations count as “cash”) up to a cumulative total for the year of $1,000 per taxpayer ($2,000 per married couple). This added deduction is in addition to the standard deduction and there is no income limitation. For non-itemizers that are not eligible to make QCD, making a donation in 2026 instead of 2025 should lower their tax bill.
For the roughly 15% of filers that itemize, the probable best action is the opposite. They may benefit from making their intended 2026 donations in 2025, particularly if they expect to be in a high tax bracket in 2026 and later. There are two new limits that affect the tax savings possible through charitable donations for itemizers made in or after 2026. First, the amount of the charitable donation that is included on Schedule A is reduced by ½% of Adjusted Gross Income (AGI). This means if you have an AGI of $500,000, the first $2,500 of your donations will not be included on the charitable deduction line of schedule A.
The second limitation applies to those in the highest tax bracket of 37%. It is a new overall limitation on the total of all itemized deductions listed on Schedule A that results in itemized deductions offsetting taxes at no higher than a 35% rate.
Dan Moisand, CFP® has been featured as one of America’s top independent fee-only financial planners by at least 10 financial planning publications and practices at one of America’s most decorated independent firms. For more info, e-mail him dan@moisandfitzgerald.com, visit moisandfitzgerald.com or call Dan at 321-253-5400, ext. 101.
Originally published on FloridaToday. Read the original article here.